 Skip to content

Deposit agreement: what you should check before signing to avoid losing thousands of euros

Buying a home is one of the most important financial decisions in our lives. However, many people make a costly mistake: signing a deposit contract without having reviewed all the important aspects of the transaction. It's common to be swept away by the excitement of finding the perfect house. The fear of another buyer getting ahead often causes people to hand over a deposit quickly, without analysing whether they can actually afford to buy that property. At Hipotea, we frequently see cases where people have paid thousands of euros as a deposit, only to discover weeks later that the mortgage has fallen through or there are unknown issues with the property. The good news is that many of these problems can be avoided if you review certain aspects before signing. What is a deposit contract? A deposit contract is a private agreement between buyer and seller whereby both parties commit to completing the purchase of a property within a specified timeframe. Typically, the buyer pays a deposit amount, which is later deducted from the final price when the sale is formalised. Although it is a common document, it should not be signed lightly, as it can have significant financial consequences if either party breaches the agreement. What happens if you breach the contract? In many sales, so-called penal deposit clauses are used, regulated under Article 1454 of the Civil Code. In such cases: This is why it is essential to verify exactly what kind of deposit the contract establishes and what its consequences are before signing. Precisely for this reason, reviewing the entire transaction before handing over money can save you headaches later. The 7 aspects you should check before signing a deposit agreement 1. Confirm that you can actually obtain the mortgage This is probably one of the most common mistakes. Many people look for a home, find their ideal house, and sign a deposit contract assuming the bank will approve their financing. But the reality is that until lenders assess your profile and the transaction, you cannot assume you will get the mortgage. Before handing over a deposit, it’s crucial to know: At Hipotea, you can make a preliminary check using our Mortgage Viability Calculator, a free tool that helps you see if your profile initially fits the criteria most financial institutions consider. 👉 Check my mortgage viability 2. Ensure the property price fits your budget Finding a home you like doesn’t automatically mean you can afford it. Beyond the purchase price, you must also consider taxes and other transaction costs, as well as the savings you might need to contribute. Before signing the deposit contract, it’s advisable to know the maximum price you can afford without jeopardising your finances. To make a first estimate, you can use our Maximum Price Calculator, which helps you gauge approximately what property price fits your financial situation. 👉 Calculate the maximum home price I can afford 3. Request an official land registry extract and check if the property has encumbrances Before handing over any money, it’s advisable to check the registration status of the property. The land registry extract provides important information such as: Spotting any such issues before signing can prevent delays and problems later. 4. Verify what documentation the property has Before committing to the purchase, request and review the relevant documentation of the property. Depending on the property and transaction, it may be crucial to check documents like: It might also be wise to verify the urban planning status and any other relevant documents depending on the specific characteristics of the property. The more information you have before signing, the fewer surprises you’re likely to encounter during the process. 5. Check the contract deadlines The deposit contract usually sets a deadline to formalise the purchase. This deadline should be realistic. A mortgage process may take several weeks to complete. The lender will need to study the documentation, perform due diligence, and usually arrange a valuation of the property before proceeding with the legal steps needed to sign. Therefore, accepting an overly tight deadline can cause problems, especially if your purchase depends on bank financing. 6. Clarify what happens if the mortgage is not approved This point is especially important. Many people assume that if the bank ultimately refuses the mortgage, they will automatically get their deposit back. This need not be the case. The outcome will depend on the contract’s content and the terms agreed between buyer and seller. Therefore, when the purchase depends on obtaining financing, it is important to carefully draft a clause related to financing approval and its consequences. This way, both parties can know beforehand what will happen if the mortgage is not obtained under the expected conditions. If you’re planning to buy your first home and require a high percentage of financing, you can also check our article on the ICO Guarantee 2026, where we explain the conditions and the importance of pre-assessing mortgage viability. 👉 Understand the new requirements of ICO Guarantee 2026 7. Calculate the mortgage monthly payment before committing Getting mortgage approval is only part of the decision. You also need to ensure that the monthly payment fits within your budget and that you can comfortably afford it. Before signing a deposit contract, you can use our Mortgage Payment Calculator to estimate monthly payments based on factors such as: 👉 Calculate my mortgage payment Knowing this information before committing to a property will help you make a much more informed decision. Mistakes to avoid before signing a deposit contract In summary, here are some of the mistakes you should try to avoid: Reviewing these points can save you financial troubles and give you much more peace of mind throughout the buying process. Checklist before
Is it possible to get a mortgage without having saved 20% of the deposit?

One of the most common phrases we hear when someone wants to buy a home is: "I’ve been told I can’t buy until I’ve saved 20%." The reality is that this isn’t always the case. While most financial institutions typically grant up to 80% of the purchase or valuation value—the lower of the two—there are situations where accessing higher financing is possible. It all depends on your financial profile, the property, and each bank’s risk policy. Why do banks usually finance up to 80%? In Spain, it’s standard for lenders to grant a mortgage of up to 80% of the value of a property intended as a primary residence. This means the buyer must provide the remaining 20%, plus have the necessary funds to cover associated purchase costs such as taxes, notary fees, registration, or valuation. This is not a legal obligation but rather a common practice by lenders to reduce the transaction’s risk. So… is it possible to get a mortgage above 80%? Yes, in certain cases. Although each transaction is studied individually, there are profiles that may qualify for financing above 80%. Some examples include: The final decision will always depend on the financial institution’s analysis. What about the ICO Guarantee? The ICO Guarantee programme remains one of the main aids to facilitate access to first homes for young people and families with dependants who meet the established requirements. It’s important to understand that ICO does not grant the mortgage. What it does is guarantee part of the transaction so that the financial entity can consider financing above 80%, provided the viability study is approved. Furthermore, some requirements have recently been expanded and the guarantee line will remain available until 2027. 👉 Discover all the changes to the ICO Guarantee: ICO Guarantee 2026: new requirements to buy your first home with up to 100% financing Having little saved doesn’t mean you can’t buy One of the most common mistakes is thinking that if you haven’t yet saved the 20% deposit, you must automatically give up on buying a home. The reality is that many variables influence a bank’s decision and each institution applies different criteria. Therefore, before ruling out purchasing, it’s worth studying your case and understanding what mortgage options you really have. What does a bank analyse before granting a mortgage? Savings are important but not the only factor a financial institution studies. Among the main factors they assess are: In short, the bank makes an overall risk assessment before approving an application. Knowing your purchasing power is the first step One of the most common mistakes is starting to visit homes without really knowing how much you can afford to buy. Knowing your purchasing power from the outset will help you save time, negotiate with more confidence, and focus solely on homes that fit your budget. You don’t need to wait to meet with a bank for this. At Hipotea, we provide several free tools to help you make an initial estimate in a few minutes. Calculate how much your mortgage repayments would be Using our Mortgage Payment Calculator, you can find out the approximate monthly payment based on the amount, term, and interest rate. 👉 Calculate my mortgage payment Discover the maximum home price you can afford Our Maximum Price Calculator estimates the approximate property amount you could afford based on your income and expenses. 👉 Calculate the maximum price of my home Check your mortgage viability If you want to know if your profile has a chance of obtaining financing before approaching a bank, you can use our Mortgage Viability Calculator. 👉 Check my mortgage viability Take the first step before house hunting The sooner you know your financing possibilities, the better decisions you can make throughout the buying process. At Hipotea, we analyse your profile individually, compare offers from multiple lenders, and help you find the mortgage best suited to your needs. Start by calculating your payment, discover the maximum home price you can afford, and if uncertain, request a personalised assessment. Buying a home starts long before signing a mortgage: it begins with good planning.
The mistake many make when signing a mortgage that could cost you thousands of euros

When someone signs a mortgage, they usually focus on a single question: what interest rate will I pay? And that is completely normal. A lower interest rate can mean significant savings over the years. However, there is a key aspect that many people overlook and that can also significantly affect their finances: the conditions for repaying or cancelling the mortgage early. It’s not all about the interest rate Comparing interest rates across different offers is essential, but it should not be the only factor to consider. Mortgages include various conditions that can make a big difference if in the future you decide to: In all these cases, there may be fees that you should know about before signing. What is an early repayment fee? Early repayment consists of paying back part or all of the loan before the agreed term. Reducing debt is usually a smart strategy, as it lowers the total interest you will pay over the life of the mortgage. However, some lenders charge a fee for doing this. Although current legislation limits these fees and many lenders now offer mortgages without early repayment charges, it remains a crucial point you should check before making a decision. What if you find a better mortgage in a few years? The mortgage market is constantly evolving. It is possible that in a few years better offers will appear than the one you initially signed. At that time, you might consider changing your mortgage to another lender through a subrogation. If your loan includes certain fees, this change might not be as financially advantageous as you expected. That’s why it’s important not only to focus on what you will pay today but also on the flexibility you will have in the future. Aspects you should review before signing Before accepting any mortgage offer, it is advisable to analyse in detail: A thorough review can help you avoid unnecessary costs in the long term. A mortgage is a long-term decision Signing a mortgage is committing to an obligation that may accompany you for decades. Therefore, beyond getting a good interest rate, it is essential to understand all the contract conditions and choose financing that gives you flexibility to adapt to any changes that may arise over time. Taking the time to compare options and resolve doubts before signing can make a significant financial difference. Are you thinking of buying a home? At Hipotea, we analyse your situation in a personalised way and compare multiple lenders to help you find the mortgage that best suits you. We explain every condition with total transparency so you can make an informed decision without surprises.
The CNMC scrutinises the mortgage market: first the banks, now mortgage brokerage
The National Commission on Markets and Competition, better known as CNMC, has again turned its attention to the Spanish mortgage market. And this time it is not only looking at banks but also at the mortgage brokerage sector. In just a few weeks, the CNMC has announced two significant actions: on one hand, the opening of sanctioning proceedings against several of Spain’s main banks for possible anticompetitive practices related to fixed-rate mortgages; on the other, an investigation into possible anticompetitive practices within the real estate credit brokerage sector. The conclusion is clear: the mortgage market is under scrutiny. And this, properly understood, can be positive for the consumer. What the CNMC has investigated in mortgage brokerage On 1 July 2026, the CNMC communicated that on 23 and 24 June it carried out inspections at the headquarters of an association of companies dedicated to mortgage brokerage. According to the CNMC itself, the investigation concerns possible recommendations, collective decisions, agreements or coordinated practices among companies in the sector that could be aimed at two particularly sensitive issues: The CNMC expressly clarifies that these inspections are a preliminary step and do not prejudge the outcome of the investigation or the guilt of any company. In other words, as of today, we are talking about an investigation, not a sanction or established infringement. This distinction is important. In competition matters, investigating indications is not the same as declaring specific companies or associations guilty. Which companies are mentioned in connection with the news The CNMC has not made public the name of the inspected association nor officially identified the affected companies. Therefore, it would not be correct to state that any specific company is being investigated without official confirmation. What is publicly known is that the Spanish Association of Mortgage Brokers, AEBH, was established in December 2024 with six founding partners: iAhorro, Finanwin, Gibobs, Grupo Financiero 10, Helloteca and Trioteca. This was published by iAhorro when announcing the association’s creation. Furthermore, on the AEBH’s own website, references appear to association meetings including associated companies such as Helloteca, iAhorro, Trioteca, Grupo Financiero 10, Hipoges and Gibobs Allbanks. However, this must be clarified precisely: a company appearing publicly as a founder or associate of a sector association does not automatically mean it has committed any infringement, nor that it is formally sanctioned, nor even that the CNMC has specifically singled it out. The relevant information for the consumer is not to rush to accusations but to understand which types of conduct concern Competition authorities and why they might affect the end customer. Why price-fixing or agreeing commercial terms would be serious Mortgage brokerage plays a very important role when done properly: it helps the customer compare banks, understand offers, negotiate terms and avoid mistakes in one of the most important financial decisions of their life. But for this role to be truly useful, there must be real competition among intermediaries. If several companies agreed on prices, fees or commercial terms, the consumer could end up paying more or having fewer options. And if companies agreed not to poach employees from each other, competition in talent, innovation and service quality could also be restricted. In other words: the problem is not that mortgage brokers exist. The problem would be if any operator in the sector, whether bank, intermediary or association, could coordinate to reduce competition. A healthy mortgage market needs banks that compete, intermediaries that compete and consumers with clear information to decide. The other major investigation: the CNMC also targets the banks This investigation into the mortgage brokerage sector comes shortly after another very significant action. On 16 June 2026, the CNMC announced the opening of sanction proceedings against Bankinter, Banco Santander, BBVA, Unicaja, CaixaBank and Sabadell for a possible practice contrary to the Competition Defence Law and the Treaty on the Functioning of the European Union. In this case, the CNMC is analysing certain public statements made by executives of these entities about banks’ future commercial policy, especially regarding fixed-rate mortgage interest rates. According to Competition authorities, these statements may have allowed other entities to anticipate the future behaviour of their competitors. Again, the CNMC reminds that opening proceedings does not pre-judge the final outcome. But the core message is clear: in the mortgage market, any conduct that may reduce competition will be monitored. What the bank and intermediary investigations have in common Although they are different cases, they share a common point: the importance of the customer being able to benefit from real competition. When banks compete, financing conditions improve. When intermediaries compete, service, transparency, technology and negotiating power improve. When the customer compares, they make better decisions. Therefore, any practice that may limit that competition harms the consumer, even if it is not always immediately visible. With a mortgage, a small difference in interest rate, in linked products, fees or expenses can mean thousands of euros over the life of the loan. What should a customer do before taking out a mortgage In this context, the consumer should not draw the wrong conclusion. It is not about distrusting all banks or all mortgage intermediaries. It is about choosing better. Before signing a mortgage, it is advisable to check several points: The best defence for the consumer is not to choose blindly, but to compare with information, advice and transparency. The role of the professional mortgage intermediary The figure of the real estate credit intermediary has been regulated in Spain since Law 5/2019, regulating real estate credit contracts. This law strengthened obligations concerning transparency, prior information and professionalism within the sector. A professional mortgage intermediary should not limit themselves to 'sending papers to the bank'. Their real function is
ICO GUARANTEE 2026: NEW REQUIREMENTS TO BUY YOUR FIRST HOME WITH UP TO 100% FINANCING
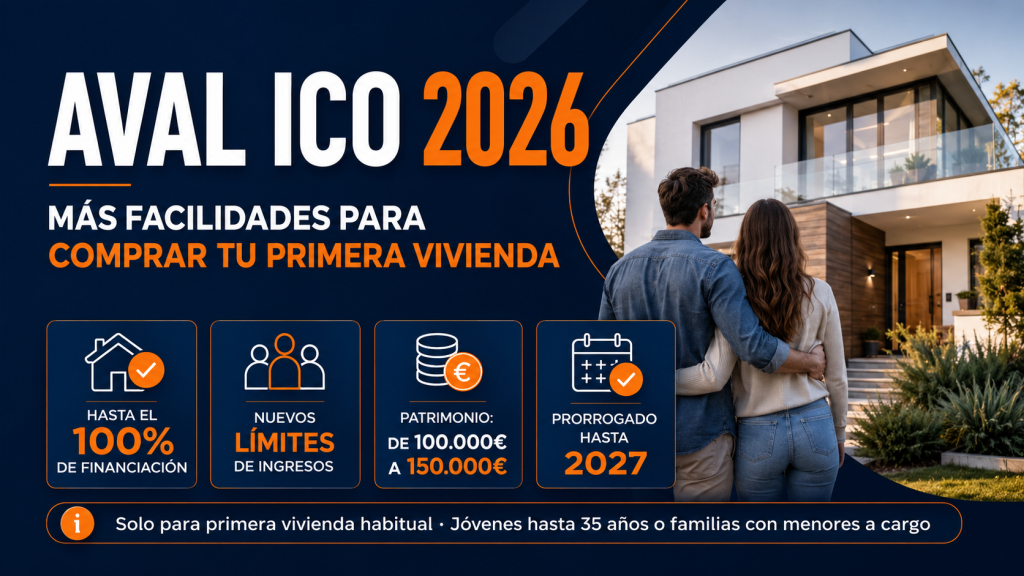
Buying a home has become one of the biggest challenges for many young people and families in Spain. The problem, in many cases, is not paying the monthly mortgage payment, but gathering the initial savings required for the purchase. Usually, to buy a property, the bank finances up to 80% of the lower amount between the purchase price and the valuation. This means the buyer must provide approximately the remaining 20%, in addition to taxes and purchase costs. For many people, that 20% deposit is precisely the barrier preventing them from buying. That is why the ICO guarantee for first homes is once again in the spotlight. The Government has reactivated and improved this line of guarantees, expanding its conditions so more buyers can access a mortgage with up to 100% financing of the property's value. In this article, we explain what the ICO guarantee is, who can apply for it, what the new requirements announced for 2026 are, which limits remain, and what you must be very clear about before signing a deposit contract or committing to buy a home. What is the ICO guarantee for buying a home? The ICO guarantee is a line of public guarantees aimed at facilitating the purchase of a primary residence for people who have the financial capacity to pay a mortgage but have not been able to save the entire required deposit. Simply put: the State guarantees part of the transaction so the bank can finance up to 100% of the home. In a traditional mortgage, the bank usually finances up to 80% of the purchase or valuation value. The buyer must provide the other 20% from their own savings. With the ICO guarantee, that 20% can be guaranteed by the State, allowing the financial institution to grant higher financing than usual. Furthermore, if the property has an energy rating of D or higher, the guarantee can cover up to 25%. This does not mean that the ICO gives you the money directly nor that the State grants you the mortgage. The bank grants the mortgage. The ICO acts as a partial guarantor of the transaction. Does the ICO guarantee allow you to buy a property without savings? Here we must be very clear: the ICO guarantee can help you buy without having saved the 20% deposit, but it does not eliminate all required savings. The guarantee can cover the part of financing that the bank would not normally lend, but it does not cover taxes or purchase costs. Therefore, although you may obtain a mortgage of up to 100% of the allowed price or value, you will usually still need money to pay these. Hence, talking about “buying without savings” can be misleading. The correct way to say it is that the ICO guarantee may allow purchasing without having saved the entire 20% deposit, provided you meet the requirements and the bank approves the transaction. Who can apply for the ICO guarantee? The ICO guarantee is mainly aimed at two profiles: Young people up to 35 years old Those who are no older than 35 at the time of formalising the mortgage can apply. If the home is bought by two young people, both must meet this age requirement. Families with dependent minors Families with dependent minors can also apply, regardless of age. This means a family with children can request the guarantee even if the buyers are over 35 years old. General requirements of the ICO guarantee Besides meeting the age or family with minors profile, there are other important requirements: It must be a first home The purchased property must be the applicant's first home. As a general rule, you cannot own another property if you want to access the ICO guarantee. There are some exceptions, for example, in cases of partial inheritance, separation, divorce, or inability to use the previous home for justified reasons. It must be a habitual and permanent residence The property must be used as a habitual and permanent residence. It cannot be for a second home, holiday home, or a property intended for investment or rental. Legal residence in Spain The applicant must be of legal age and have legal residence in Spain, continuously accredited during the required period. The operation must be approved by an affiliated bank The ICO guarantee is not applied for directly from ICO by the client. It is processed through financial institutions affiliated with the guarantee line. This is very important because not all banks handle it the same way, not all have the same agility, and some may apply more stringent internal criteria. What has changed in the ICO guarantee in 2026? The big news is that the Government has announced improved conditions to increase the number of people who can access the guarantee. Until now, the general income limit was approximately 37,800 gross euros annually per applicant. With the announced changes, that limit will no longer be uniform across Spain and will adapt to the economic effort required to buy property in each province. This is important because buying a home in Madrid, Barcelona, Málaga, the Balearic Islands, or certain high-demand areas requires a different income level than buying in other provinces with lower prices. The measure attempts to correct this issue: people with incomes higher than the previous limit could still need help to buy, especially in areas where housing is much more expensive. Announced new income limits According to published information, the new income limits will be organised by provinces or zones, potentially reaching up to 63,000 gross euros annually in provinces with the greatest difficulty in accessing housing. For example, in areas like Madrid or Barcelona, the limit could rise from the previous 37,800 gross euros annually up to 63,000 gross euros annually per applicant. This represents a very significant change because it allows profiles that previously were excluded for exceeding the income limit to now apply for the
The CNMC investigates six major banks over fixed-rate mortgages: what is happening and how it may affect you
Were the mortgages from the big banks all moving too similarly? The news has shaken the Spanish mortgage market: the National Commission on Markets and Competition, the CNMC, has opened an investigation into six major Spanish banks for possible anti-competitive practices related to fixed-rate mortgages. The banks under investigation are Santander, BBVA, CaixaBank, Sabadell, Bankinter, and Unicaja. And although this is still an investigation, not a conviction, the case is significant enough that anyone looking for a mortgage might ask a very simple question: Are the banks truly competing to offer me the best mortgage, or are they all moving too similarly? That is the core issue. What exactly is the CNMC investigating? The CNMC is not saying the banks are guilty. It is important to be clear about that from the start. What the Competition authority has done is open sanction proceedings to analyse whether some public statements made by directors of these entities could have affected competition in the mortgage market. The focus is especially on fixed-rate mortgages. The suspicion is not so much the classic image of “secret meetings” between banks, but something more subtle: public statements about the future commercial policies of the entities. Put simply: Competition wants to know whether certain messages publicly released by some banks may have allowed the rest of the entities to anticipate what would happen with mortgage offers and thus avoid a real price war. Because if everyone knows where the others will move, the pressure to lower prices can be lessened. And when competition decreases, usually the consumer loses out. Why this case is so relevant to mortgage seekers A mortgage is not just any product. For most families, it is the most important financial decision of their life. We are not talking about choosing a mobile tariff, car insurance, or a bank account. We’re talking about debt that can accompany you for 20, 25 or 30 years. Therefore, if mortgage conditions are too similar among the major entities, the buyer may have a false sense of comparison. They go to their bank. Then ask another major one. Then consult a third. And in the end, they might think: “If they all offer me something similar, this must be the best available.” But that conclusion may be mistaken. That several offers resemble each other doesn't necessarily mean they are the best in the market. It could simply mean you are comparing within too narrow a circle. And here lies one of the great lessons from this news: comparing mortgages is not about going to three well-known banks and picking the least bad. To compare properly is to analyse the entire market, understand which entity really wants your transaction, study the actual conditions, and not be swayed just by the bank’s name. The apparent contradiction: Spain has competitive mortgages, yet banks are under investigation One argument from the banks is that the Spanish mortgage market is very competitive compared to other European countries. And that argument should not be ignored. Spain has had very attractive mortgage rates in recent years, especially in certain profiles and operations. In fact, some entities have offered very aggressive conditions to attract good customers, particularly on fixed and mixed mortgages. But that the Spanish market is generally competitive does not prevent Competition from investigating whether, at a specific moment, certain public statements could have distorted that competition. These two ideas are compatible. A market can be competitive and simultaneously be under investigation to see if any players have sent signals reducing uncertainty among competitors. The key is not only whether mortgages are expensive or cheap compared to Europe. The key is whether each bank freely decides its offers or if certain public communications could have influenced the behaviour of the rest. The most delicate point: speaking publicly can also influence the market When we think of anti-competitive practices, we usually imagine explicit pacts, private meetings or direct agreements. But in concentrated markets, where few players have significant weight, the information communicated publicly can also be relevant. If a major entity publicly says that certain mortgages are unprofitable, that there is no point in lowering prices further, or that it will tighten its commercial policy, that message can be heard by customers, analysts, investors… and also by competitors. That is the point analysed by the CNMC. It is not just about speaking. It is about whether those messages might have allowed other banks to anticipate future decisions and adapt their strategy without direct coordination. It’s a fine but very important line. And that is why the proceeding may take months to resolve. What could happen now From here, a process begins that could last up to 24 months. During that time, the CNMC will have to analyse the facts, review statements, assess the context, hear from the entities and determine whether there was truly conduct against competition. It is also important to be clear that opening proceedings does not imply guilt. It can end with a sanction, without one, or with an intermediate result. Some sector analysts even consider the risk of significant penalties for the banks may be limited. But that does not reduce the importance of the matter. Because, beyond whether a fine ultimately occurs or not, the proceeding raises a question that directly affects the consumer: Is the homebuyer receiving real competition among banks or just the appearance of competition? The key fact: six entities with enormous market weight Santander, BBVA, CaixaBank, Sabadell, Bankinter, and Unicaja are not minor entities. We are talking about six of the major players in the Spanish mortgage market. According to published data on the mortgage business for 2025, these entities would concentrate around 67% of the market, that is,
What influences a property valuation the most?
The 10 Factors That Can Increase or Decrease a House's Valuation When You Apply for a Mortgage When someone buys a home, they usually focus on very personal aspects: renovations, the terrace, the views, the number of bedrooms, the area, the layout, or simply the feeling the property gives upon entering. And that is perfectly normal. Each buyer values some things more than others. But if you are purchasing with a mortgage, there is one reality you must be very clear about: the bank does not only consider the price you agree with the seller. It also takes into account the value that a valuer can justify. That difference can be decisive. You might think a property is worth a certain price because you like it, because there is limited supply, or because the seller refuses to negotiate. However, to grant a mortgage, the financial institution requires a valuation carried out according to technical and regulatory criteria. And if the valuation comes in below the purchase price, the transaction may become complicated. In this article, we explain which factors most influence the valuation of a home, why some weigh more than others, and what you should review before reserving a property. What Is a Mortgage Valuation? A mortgage valuation is a technical appraisal of the property used to determine its value as collateral for a mortgage loan. It is not the buyer’s opinion. It is not the price the seller is asking. It is not simply what is listed on a property portal. Nor is it just 'what is being paid in the area.' The valuation must technically justify the property's value considering its characteristics, documentation, condition, location, and comparable market. Applicable Regulations: Order ECO/805/2003 and Order ECM/599/2025 In Spain, mortgage valuations are conducted in accordance with Order ECO/805/2003, of 27 March, which regulates property valuation standards and certain rights for specific financial purposes. This regulation was amended by Order ECM/599/2025, dated 10 June, published in the Official State Gazette (BOE) on 12 June 2025 and effective from 12 August 2025. The 2025 reform strengthens key aspects such as the documentation used by the valuer, traceability of comparables, surface area justification, energy efficiency certification, and the principle of sustainability. Important: The regulation does not publish an official ranking of factors from 10 to 1. What it does establish is what the valuer must review and justify. Therefore, this article’s ranking is a practical ordering based on the criteria that usually have the greatest influence in a housing mortgage valuation. Key Idea A valuation does not depend solely on the condition of the home. It depends on its size, building, location, documentation, and what the comparable market allows to be justified. Ranking: The 10 Factors That Most Influence a Home Valuation 10. Energy: Energy Efficiency, Insulation, and Consumption Energy efficiency is increasingly important in a property's valuation. The energy certificate, insulation, type of windows, heating and cooling systems, estimated consumption, and emissions can influence the perception and value of the property. Furthermore, with the 2025 regulatory update, the energy efficiency certificate gains increased relevance as documentation within the valuation process. However, in a standard property, energy still typically weighs less than other factors such as location, size, building, or market comparables. Hence it is number 10: it matters more and more, but it is usually not the factor that determines the final value the most. 9. Condition and Renovation The condition of the property clearly influences the valuation. A renovated, well-maintained home with updated installations, good bathrooms, modern kitchen, efficient windows, and materials in good condition can be valued higher than a similar property that needs a full renovation. But there is a very common mistake: thinking that all money spent on renovation is automatically recovered in the valuation. This does not always happen. The valuer does not only assess the cost of the work but the value that improvement adds to the property within its market. Renovations add value but do not replace stronger factors such as location, size, or comparable market. 8. Floor Level The floor level also has an influence, but not always in the same way. A high floor with a lift is usually valued better because it generally has more light, better views, less street noise, and more privacy. But if the building has no lift, the floor level can significantly penalise the valuation. It is not the same to be on the first floor without a lift as on the fourth floor without one. Ground floor properties may be penalised for less privacy, less light, more noise, or a greater sense of insecurity, although in some cases a courtyard or separate access can compensate for some of that disadvantage. 7. Light and Views Orientation, natural light, whether the property is interior or exterior, and its views can substantially influence the valuation. A bright home usually has better perception, better habitability, and greater commercial appeal. Good views can make significant differences: sea, park, square, mountain, historic area, or unobstructed views. However, views do not carry the same weight in every property. In a beach property, a penthouse or premium home, they can be very significant. In other cases, they contribute but usually do not outweigh size, location, or comparables. 6. Extras: Garage, Storage Room, Terrace, Courtyard, Pool, or Common Areas Extras can make a clear difference. Garage, storage room, terrace, courtyard, pool, garden, or common areas can increase a property's appeal. The key lies in whether these extras are scarce or not in that area. A garage can be very valuable in the centre of a city where parking is difficult. A terrace can have considerable weight in neighbourhoods where very few properties have outdoor space. Therefore, extras are not valued in isolation: they are assessed within the specific market of the property. 5. Layout:
Switching your mortgage to another bank: when it makes sense, what costs are involved, and which option to choose
Changing a mortgage from one bank to another can be one of the most important financial decisions for a family. It is not just about paying a lower monthly payment. It involves knowing whether you can improve your interest rate, reduce ties, change the type of mortgage, increase the capital, or even better reorganise your debts. The key lies in thoroughly analysing the operation, because changing the mortgage can mainly be done in two ways: Both options can serve to improve conditions, but they do not have the same costs, the same timelines, or the same flexibility. What does changing a mortgage from one bank to another mean? Changing a mortgage from one bank involves transferring the financing to another entity to improve the current conditions. Usually, one of these objectives is sought: But not all these options fit equally in a subrogation. That is why choosing the route wisely is so important. Mortgage subrogation: it can be cheaper, but also slower and with fewer banking offers The creditor subrogation consists of changing the mortgage bank without cancelling the current loan. That is, a new entity takes the place of the bank you currently have. Its main advantage is that it generally incurs fewer expenses than cancelling the mortgage and signing a new one. Normally, the client's cost is focused on the valuation and, if applicable, on the agreed commission in the deed. But it has two significant drawbacks. The first is the timeframe. The subrogation is not signed immediately. Once the offer from the new bank is obtained, the current entity must be notified and has legal deadlines to intervene in the process. Specifically, it has 7 calendar days to deliver the debt certificate and then 15 calendar days to be able to present an improvement or matching offer of conditions. During that period, the subrogation cannot be formalised. The second drawback is that not all entities handle subrogations. And this is very important. Many entities prefer not to offer this path because they assume a clear commercial risk: they may study the operation, approve it, issue the offer and dedicate resources to the file only for the current bank to ultimately match or improve the conditions and the client decides to stay where they are. In that case, the new bank has done all the work but does not sign the mortgage. Therefore, although subrogation may seem the most logical option due to lower costs, in practice it reduces the number of banks available. It is not enough to say: “I want a subrogation because it is cheaper”. You must check which entities actually offer this option, which do not work with it, and whether the conditions they offer compensate compared to a cancellation with a new mortgage. The conclusion is clear: subrogation can be a good option when the main goal is to improve the interest rate or term and there is no rush. But if speed, more flexibility, or access to a greater number of banking offers are sought, it is often advisable to also consider cancellation and signing a new mortgage. Cancelling the mortgage and signing a new one: it usually costs a bit more, but allows more leeway The other option is to cancel the current mortgage and sign a new mortgage with another bank. This route usually entails more expenses because the old mortgage must be officially cancelled and a new one constituted. But in practice many clients prefer it for three reasons: Therefore, decisions should not be based solely on cost. One must decide based on the objective. If the only goal is to improve interest rate and term, subrogation may suffice. But if the client wants to change more aspects of the operation, ask for more money, or simplify debts, it often makes more sense to cancel and sign a new mortgage. Differences between subrogation and cancellation with a new mortgage Aspect Subrogation Cancellation + new mortgage What happens You change the mortgage bank You cancel the current mortgage and sign a new one Typical cost Lower Higher Speed Usually slower Usually faster Current bank May try to retain the client Does not have the same subrogation process Possible changes Mainly interest rate and term Allows redesigning more aspects of the operation Increasing capital More limited More common Best for Improving conditions while maintaining structure Revising the mortgage or asking for more money What costs does a mortgage subrogation have? In a subrogation, the client normally needs to consider these costs: Expense Usually paid by Property valuation Client Subrogation or early repayment commission, if applicable Client Notary fees for the mortgage deed New bank Registry of the mortgage guarantee New bank Administration fees New bank Documentary Stamp Tax According to applicable tax regulations, normally assumed by the entity under legal terms Law 5/2019 establishes that valuation costs correspond to the borrower, while administrative fees, notarial fees for the mortgage deed, and registration costs correspond to the lender. Therefore, in many cases the actual cost of a subrogation for the client concentrates on two concepts: valuation and the possible commission on the current mortgage. What commission can be charged for changing the mortgage? The commission depends on the signing date, type of mortgage, and what was agreed in the deed. Furthermore, even if the deed includes a commission, the entity can only charge within the applicable legal limits. Type of mortgage / date Indicative maximum commission Old variable mortgages subject to Law 2/1994 Up to 1% in certain cases Mortgages signed from 27 April 2003 at variable rate Up to 0.50% on subrogation, if applicable according to the deed Mortgages signed from 9 December 2007 Up to 0.50% during the first 5 years and up to 0.25% afterwards, as compensation for early cancellation Variable mortgages signed from 16 June 2019 Up to 0.25% during the first 3 years or up to 0.15% during the first 5, depending on the agreement Change from variable to
Buying a house now or waiting: what the May 2026 data tells us
Buying a home has always been an important decision, but in 2026 it has become especially challenging. On one hand, sales are starting to slow down. On the other, prices remain at record highs. While many buyers are hoping for a clear drop in house prices, the euribor reminds us that financing conditions can also change direction. The inevitable question is: is it advisable to buy a home now, or is it better to wait? The answer does not lie in any miraculous market prediction. It lies in understanding what the data says and, above all, in knowing whether your mortgage arrangement is viable today. Fewer homes are being sold, but the market hasn't stopped The latest published data shows a certain slowdown in the real estate market. According to the INE, in March 2026 there were 61,295 home sales registered, 2.2% fewer than in the same month the previous year. Furthermore, new home sales fell the most, with an annual drop of 10.2%, while second-hand home sales remained practically stable. At first glance, this data might suggest that the market is starting to cool down and that waiting could be a good strategy. But the reading is not so straightforward. A moderate decrease in sales does not necessarily mean an immediate price drop. It could indicate that fewer buyers are able to complete a purchase, that financing has become more demanding, or that many families cannot align price, savings, and monthly payment. In other words: the market is moderating, but not collapsing. And that significantly impacts the decision. The problem is that prices continue to rise Here lies the major contradiction of the moment: fewer homes are selling, yet prices are not falling broadly. According to idealista, the price of second-hand homes in Spain rose by 16.9% year-on-year in April 2026, reaching €2,748 per square metre, the highest level since the portal began recording data. This data should not be interpreted simplistically. We are talking about asking prices, not always the final closing prices. Yet even with that nuance, the trend is clear: sellers are not generally lowering prices. The reason is simple: in many areas, housing supply remains low, demand is accumulated, and buyers with sufficient resources compete for the most attractive properties. Therefore, waiting just because “one day prices will have to fall” can be risky. It may happen that in a few months there are fewer transactions, but the home you want is not cheaper. It might even be more expensive or no longer available at all. The euribor is adding pressure again The second key factor is financing. For many months, some buyers have trusted that mortgages would continue to become cheaper. However, in May 2026, the euribor rose above last year’s levels again. As of 19 May 2026, the provisional monthly average euribor was around 2.8%, compared to about 2.08% in May 2025. This does not mean all mortgages will become equally more expensive, but it does have important consequences. If the euribor rises, variable-rate mortgage payments can increase. It may also affect mixed-rate mortgages and some lenders’ commercial strategies. Most importantly, it may reduce a family’s purchasing power if the maximum affordable monthly payment tightens. Put simply: if house prices don’t fall and financing becomes more expensive, waiting may not improve your situation. Banks do not lend equally to all buyers Another common mistake is thinking there is “the best mortgage” as if it were the same for everyone. It doesn’t work like that. Two buyers can go to the same bank, request financing for similar properties, and receive very different conditions. It depends on their income, job stability, savings, debt, age, type of property, financing percentage, valuation and risk profile. Moreover, banks may compete for good profiles, but they are not obliged to approve poorly structured cases. The difference between buying well or badly is usually not just the interest rate. It lies in properly preparing the operation before reserving the property. The big mistake: signing a deposit agreement before knowing if the mortgage is viable In a market with limited housing availability, many buyers feel pressured. They see a home they like, fear losing it, and sign a deposit agreement without thoroughly analysing their financing. Problems then arise: the valuation falls short, the bank does not finance as expected, the monthly payment exceeds recommended limits, or unexpected costs appear. This is one of the most costly mistakes a buyer can make. Before signing a deposit agreement, you should clearly know: The question should not just be whether to buy now or wait. The correct question is: Can I buy this home with certainty? When buying now may make sense Buying now may make sense if you find a home that suits you, have job stability, sufficient income, reasonable savings, and an affordable monthly payment. It may also make sense if you are paying high rent and there are no clear signs that waiting will offer you a better opportunity. In that case, delaying the decision may have a cost: additional months of rent, possible price increases, less available supply, or less favourable mortgage conditions. But buying now is only a good decision if the numbers add up. Buying out of fear that everything will rise can be as dangerous as waiting forever for a drop that never comes. When waiting may be better Waiting can be the wisest choice if your financial situation is too tight. For example, if you have little savings, require very high financing, have unstable income, have outstanding personal loans, or the mortgage payment approaches the recommended limit. It may also make sense to wait if you plan to improve your profile in the coming months:
Which banks are currently offering the best mortgages?
When you start looking for a mortgage, it’s normal to ask yourself this question: Which bank is currently offering the best conditions? The answer seems straightforward, but it isn’t. Two people can go to the same bank, request a similar mortgage, and receive completely different responses. One may secure a very competitive offer while the other may face more ties, a worse interest rate, or even a refusal. Why does this happen? Because banks don’t only analyse the property you want to buy. They review your complete profile: your income, job stability, savings, debt level, the financing percentage you need, the location you’re buying in, and the type of operation you propose. Therefore, finding the best bank for a mortgage isn’t just about looking at who advertises the lowest interest rate. It’s about knowing which institution can approve your operation and offer you good conditions according to your particular case. In Spain, there are three main types of entities it’s worth knowing before choosing a mortgage: Each group operates differently. And within each group, each entity can have very different criteria. The question isn’t which bank is better, but which one fits you Best. It’s not the same to be a civil servant with sufficient savings as a self-employed with variable income. It’s not the same to buy a primary residence as a second home. It’s not the same to request 70% of the purchase price as to need higher financing. Nor is it the same a straightforward operation as a purchase with more variables: change of residence, pending sale, multiple holders, supplementary income, financing of expenses, CIRBE incidents or needing to properly justify repayment capacity. A mortgage is not granted merely by the advertised rate. It is granted after analysing the risk of the operation. And each entity has its own way of doing this. Therefore, the right question is not just: “Which bank gives the best mortgage?” The truly important question is: “Which bank can give me the best mortgage personally?” Comparative table: traditional banks, digital banks and rural banks Type of entity Main advantages Possible drawbacks When it may fit best Traditional banks These are very well-known entities, with branches, infrastructure, and mortgage experience. They can offer good conditions to solvent profiles and clear operations. They tend to be more demanding regarding financing, indebtedness, job stability, and ties. They are not always the most competitive. When you have stable income, good savings, low indebtedness, or a strong previous relationship with the entity. Digital banks More agile, convenient, and online processes. They can work well with simple operations and very clear profiles. They offer more standardised solutions and less personalised advice when the operation requires explanation or tailored analysis. When you have a stable contract, good financial profile, simple documentation and don’t need a complex operation. Rural banks and cooperatives They can offer very interesting conditions in certain areas or for specific profiles. There are over 30 spread throughout Spain and they vary greatly from one another. Not all seek the same profiles nor offer the same solutions. They usually require more ties and you need to know which one may fit. When buying in a specific area, you need an entity with local knowledge or your profile fits their risk policy. This table summarises a key idea: it’s not about choosing the most famous bank, but the entity that can really offer you good conditions according to your profile. Traditional banks: well-known, strong, and demanding Traditional banks tend to be the first option for many buyers. It’s logical: these are familiar entities, many people already have their salary, bills or savings there, and they convey a sense of security. Furthermore, they have infrastructure, a branch network, mortgage teams, and capacity to analyse different kinds of operations. But that doesn’t mean they are always the most competitive option. They can work well when the client has a solvent profile, good job stability, sufficient savings and a clear operation. They can also be interesting if there is a prior relationship with the entity and the bank positively values the client’s history. The main drawback is that they tend to be demanding. They can analyse quite strictly the percentage of financing, indebtedness, job stability, contract type, income seniority or previous ties with the entity. Also, often the best conditions are linked to additional products: insurance, cards, salary direct debiting, pension plans or other services. This is not necessarily negative, but it must be calculated carefully. A mortgage may look attractive due to its interest rate, but if it requires expensive or unnecessary products, the real cost can change significantly. Digital banks: agile, convenient, and more standardised Digital banks have gained prominence because they offer simpler processes, fewer trips and a faster experience for many clients. In clear-cut operations, they can be an interesting option. A digital bank can work well when the profile is very clear: permanent contract, stable income, low indebtedness, sufficient savings, reasonable financing, straightforward documentation and an operation without significant peculiarities. In these cases, digital agility can be an advantage. The client can progress faster, send documentation online and receive a first response comfortably. The problem arises when the operation needs more personalised analysis. For example: self-employed with variable income, several holders, high financing, change of residence, purchase conditional on sale, supplementary income or situations where the entity needs to understand the case beyond a form. In such operations, an overly standardised solution may fall short. Digital banks aren’t bad. They simply aren’t always the best path when the client needs someone to thoroughly analyse and advocate for their operation. Rural banks and cooperatives: the opportunity many buyers overlook This is one of the least known points by many buyers. When talking about mortgages, most think of the most famous banks. However, in Spain there is a broad ecosystem of rural banks and credit cooperatives that can be very interesting for certain operations. We are talking about over 30 entities distributed throughout Spain,