Skip to content

When someone takes out a mortgage, they usually focus on a single question: ‘What interest rate will I pay?’
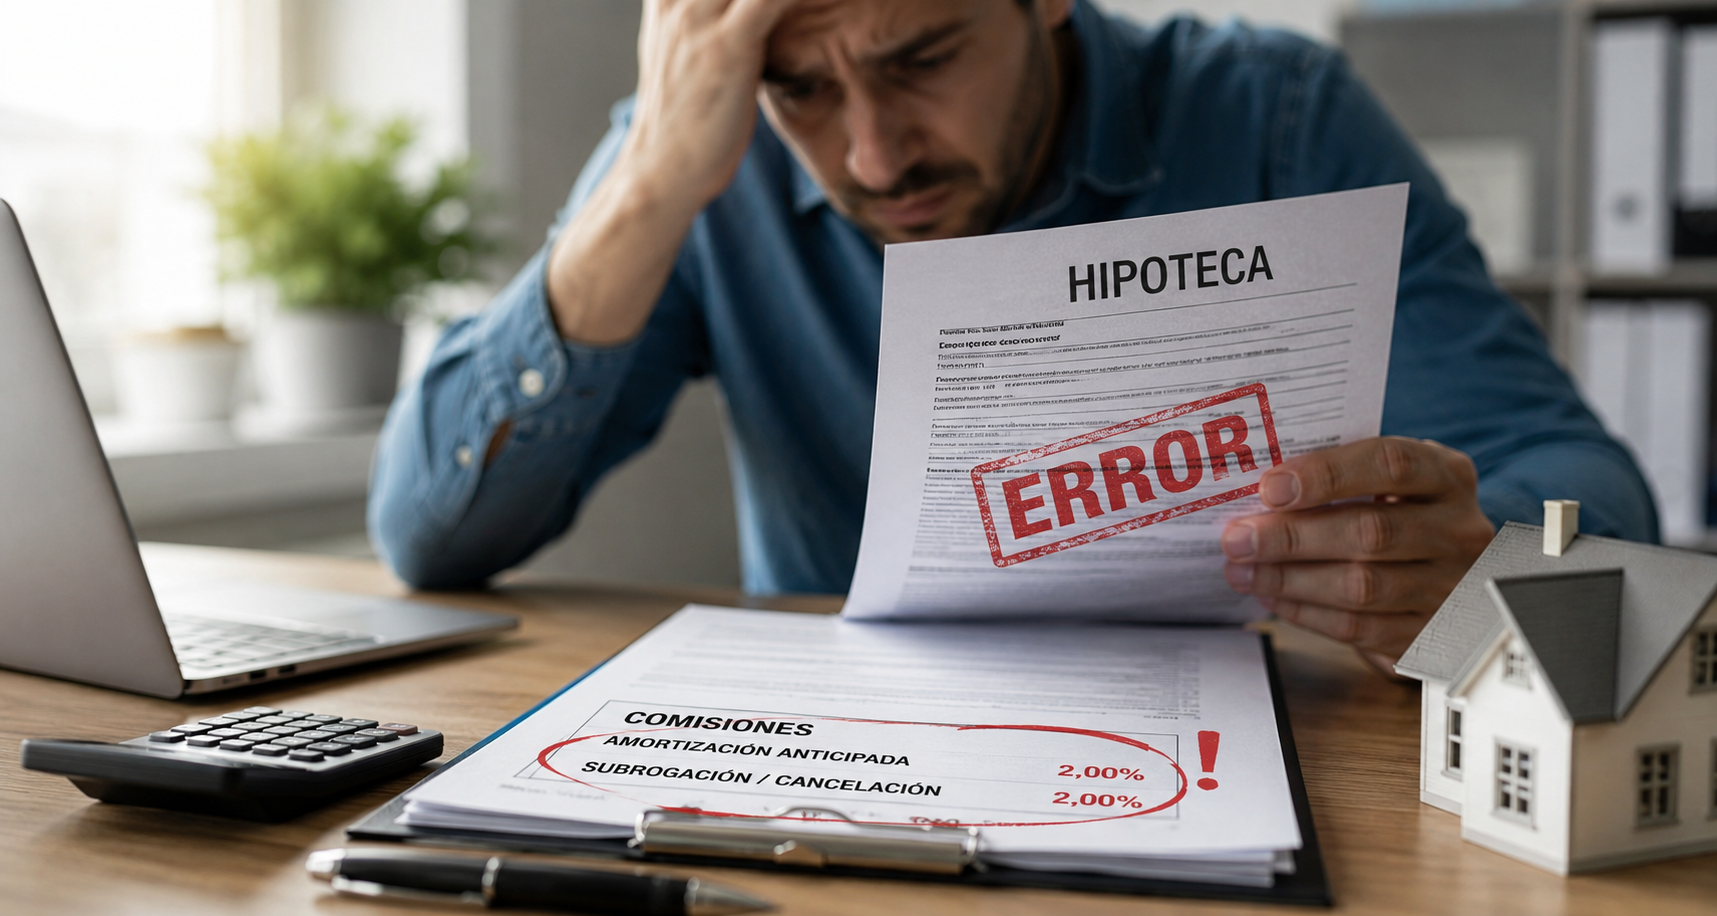
And that’s entirely normal. A lower interest rate can mean significant savings over the years. However, there is a key aspect many people overlook that can also significantly affect their finances: the conditions for repaying or cancelling the mortgage early.
It’s not all about the interest rate
Comparing interest rates between different offers is essential, but it shouldn’t be the only factor considered.
Mortgages include various conditions that can make a big difference if in the future you decide to:
- Make partial repayments to reduce debt.
- Cancel the mortgage before the term ends.
- Switch your mortgage to another bank to improve conditions.
- Sell the property before finishing paying off the loan.
In all these cases, fees may apply that you should be aware of before signing.
What is an early repayment fee?
Early repayment means paying back part or all of the loan sooner than scheduled.
Reducing debt is usually a smart strategy as it decreases total interest paid over the mortgage term. However, some lenders charge a fee for carrying out this operation.
Although current legislation limits these fees and many lenders now offer mortgages without early repayment costs, it remains a key point to review before making a decision.
What if you find a better mortgage in a few years?
The mortgage market is constantly evolving.
It’s possible that in a few years better offers will appear than the one you initially signed. At that point, you might consider switching your mortgage to another lender through subrogation.
If your loan includes certain fees, that change might not be as cost-effective as you expected.
That’s why it’s important not only to focus on what you’ll pay today but also on the flexibility you’ll have in the future.
Aspects you should review before signing
Before accepting any mortgage offer, it’s advisable to carefully analyse:
- The interest rate and the APR (TAE).
- Mandatory tie-ins (insurance, cards, salary account or additional products).
- Early repayment fees.
- The conditions for cancelling or transferring the mortgage.
- The possibility of making partial repayments without penalty.
A thorough review can help you avoid unnecessary long-term costs.
A mortgage is a long-term commitment
Taking out a mortgage means assuming a commitment that can last decades.
Therefore, beyond getting a good interest rate, it is essential to understand all contract conditions and choose financing that gives you flexibility to adapt to possible changes over time.
Spending time comparing options and clearing up doubts before signing can make a big financial difference.
Are you thinking about buying a property?
At Hipotea, we analyse your situation personally and compare offers from multiple lenders to help you find the mortgage that best suits you. We explain every condition transparently so you make an informed decision without surprises.