Skip to content

The Spanish property market is going through a critical moment, with prices reaching historic highs and increasing difficulty for many families to access home ownership. This situation has led experts and property developers to warn of a possible sector collapse within three years if effective solutions to improve financial accessibility are not found. A controversial proposal now emerging is ultra-long mortgages, lasting up to 70 years. What do these mortgages really mean and what are their real implications for the market?
What is a 70-year mortgage?
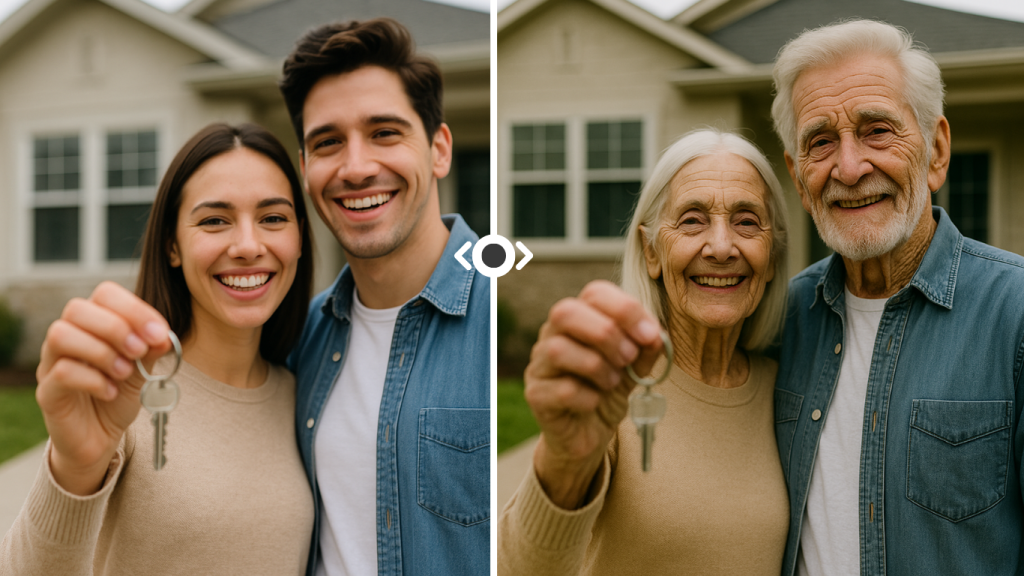
A 70-year mortgage is a financing option that allows the repayment term to extend almost for the borrower’s entire lifetime, aiming to minimise the monthly payment and facilitate access to higher-value homes. This type of loan is especially aimed at young buyers or those with lower financial capacity, and although it is currently debated, it is not entirely new: before the 2008 crisis, similar products were offered in Spain known as inheritable mortgages. Back then, such products were colloquially called inheritable mortgages because the sum of the borrower’s age and the mortgage term exceeded average life expectancy by far.
This type of long-term financing is beginning to emerge as an alternative to more traditional mortgage types, especially for young people seeking to buy their first home. But what if this kind of mortgage is actually designed to help you temporarily and not to be maintained for 70 years?
Advantages of ultra-long mortgages
- Significantly lower monthly payments: A €200,000 mortgage at 2.5% interest would have an approximate monthly payment of €790 over 30 years, whereas stretching the term to 70 years would reduce this to around €504 per month.
- Expanded accessibility: Enables home purchase for segments like young people, families with moderate incomes, or more limited financial profiles.
- Greater purchasing power in real estate: The reduction in monthly payments allows acquisition of higher-value homes compared to shorter mortgage terms.
- Greater immediate financial flexibility: Lower monthly payments allow buyers to allocate more resources to other essential expenses or investments.
Disadvantages and associated risks
- Prolonged indebtedness: Such mortgages imply many borrowers will be paying off their home at retirement age or may even leave the debt as an inheritance.
- Increased total cost: Due to the long loan duration, the total amount paid in interest will be considerably higher.
- Elevated financial risk: Ultra-long mortgage terms can increase the risk of over-indebtedness both at family and macroeconomic levels, especially in times of economic uncertainty.
Is history repeating? Comparison with the 2008 crisis
Before the 2008 financial crisis, Spain experienced a similar situation, with a large supply of mortgage credit with excessively long terms, financing up to 100% of the appraised value, and lax conditions for granting loans. These practices were fundamental in creating a real estate bubble that had devastating consequences for the Spanish and global economy.
Currently, there are concerning similarities:
- Increasingly lax credit conditions: Although more regulated than before, some financial institutions are excessively loosening their requirements to grant mortgage credits.
- High real estate inflation: Elevated prices and overly optimistic valuations may be driving market overvaluation.
- Excessive credit dependence: Extreme dependence on mortgage credit could reproduce economic vulnerabilities experienced in the past.
Although current regulation imposes more controls — such as those established by Basel III or the Spanish Mortgage Law — some past dynamics are reappearing with a different veneer.
What are the usual and effective mortgage terms in Spain?
While traditionally mortgages in Spain are offered with terms close to 30 years (with occasional exceptions up to 40 years), normally the sum of the applicant’s age plus the mortgage term does not exceed 75 years, although some financial institutions allow exceptions that may take this sum up to 80 years under specific conditions.
In practice, according to official data from the Spanish Mortgage Association and the College of Registrars, the actual average duration of mortgage cancellations in Spain is approximately 20 years. This term is shorter mainly due to early repayments or early property sales. Therefore, even with initially long terms, most mortgages do not reach the end of the contracted period. This information could be interpreted as an argument in favour of the ultra-long term mortgage model, whose main objective is to facilitate more affordable monthly payments. Additionally, these extended terms are particularly useful for younger people acquiring their first home, which usually will not be their permanent one, thus facilitating future sale and early loan cancellation.
Real solution or new financial risk?
Ultra-long mortgages are proposed as an immediate response to the growing problem of housing accessibility. Although they seem a practical solution for many families, with lower payments and the possibility to access more expensive homes, they also carry considerable risk. The market could experience greater price pressure by facilitating financial access to more buyers, generating additional demand that could further drive property inflation and worsen the current situation.
In this article we have discussed term length, but choosing a mortgage goes much further. There are many other equally important variables: the interest rate, the buyer’s profile, the property value, tie-ins or even personal and family medium- and long-term goals. At Hipotea we will be happy to provide a free and completely personalised study to analyse your case and help you find the best option on the market, tailored to you.