Skip to content

In just a few days, the mortgage market has changed more than many expected.
And this has a direct consequence:
Decisions that seemed right just a few weeks ago… can now be costly.
It doesn't matter if you already have a mortgage or are about to sign one.
What matters now is not what is happening… but what you do with your mortgage from this point on.
Change how you view your mortgage
One of the biggest mistakes is thinking that a mortgage is a decision you make once and it's done.
It isn't.
It is a financial product that should be reviewed when the context changes.
And that is exactly what has just happened.
If you already have a mortgage
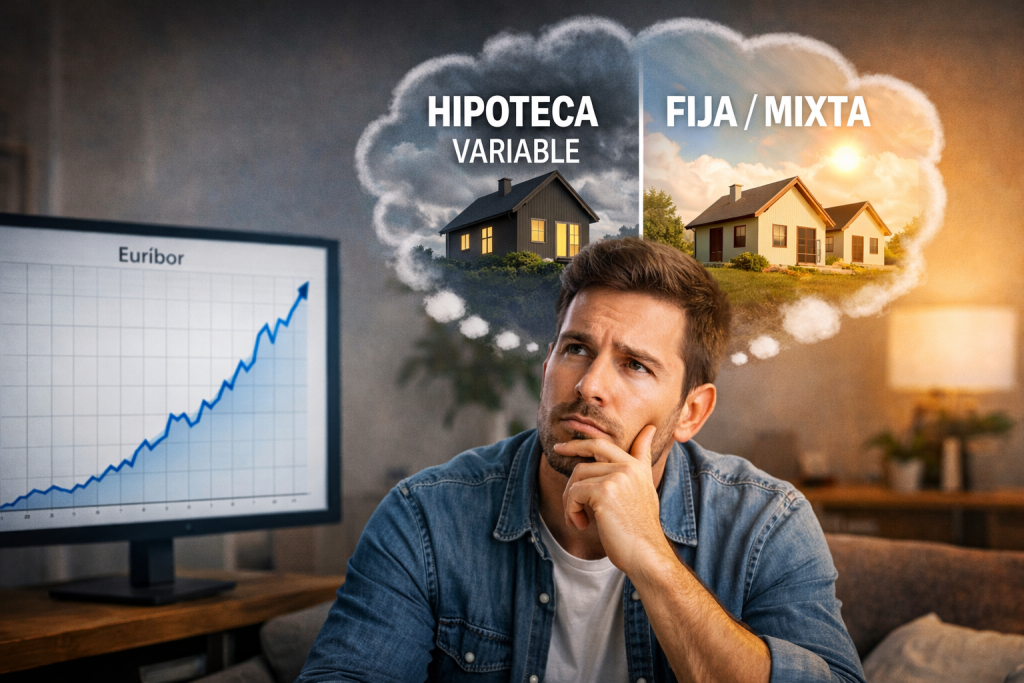
Pay special attention if it is variable
Today, with an average margin close to 0.8% over Euribor, many mortgages are already—or will be reviewed—above 3%.
And the relevant point is not just that figure.
The scenario has become unpredictable.
Does it make sense to change now?
In many cases, yes. But not for everyone.
It starts to be interesting if you can access:
- A fixed-rate mortgage equal to or below 2.5%
- Or a mixed mortgage from approximately 1.40% for 10 years
In the current context, the mixed mortgage is, in many cases, the most efficient option.
Because it allows you to pay less now, protect yourself in the coming years, and maintain room for improvement in the future.
The filter that really matters
Improving the interest rate alone is not enough.
For the change to make real sense, two conditions usually need to be met:
- Outstanding amount above €100,000
- Remaining term of at least 15 years
If these are not met, the impact of the change may be limited, as more capital than interest is repaid at that stage.
How to change your mortgage
Novation (with your bank)
This involves negotiating a change to the mortgage terms with your current bank.
The cost is usually low and mainly depends on whether there is a novation fee stipulated in the deed.
In practice, banks rarely improve conditions without pressure, so it is normally necessary to have an offer from another institution for them to consider the change.
Subrogation (change bank)
Another bank takes over your mortgage, improving the conditions.
Costs are usually low, but there is a key point to consider:
Once you have an offer, your current bank has 15 calendar days to match it.
During that period you cannot sign with the new lender, which introduces uncertainty into the process.
Additionally, many banks do not prioritise this route due to the risk that the operation may not be finalised.
Cancellation and new mortgage
It involves cancelling the current mortgage and formalising a new one.
Costs range approximately between €1,000 and €1,500 (notary, registry, and management fees), but this is often a faster process with a higher probability of obtaining better conditions.
In many cases, this is the most effective way to achieve a real improvement.
If you are looking for a mortgage
The most common mistake at this time is waiting.
Many buyers think the best option is to delay the decision, hoping rates will decrease.
But the market has shown that scenario does not always come to pass.
What to do now
Currently:
- Fixed-rate mortgages are only interesting if obtained below 2%
- Mixed mortgages are, in many cases, the best option
With real offers around 1.40% for 10 years.
A key idea
A mortgage is not a decision for life.
It is a decision that can be reviewed and improved over time.
Therefore, the important thing is not to get it right once, but to make the best decision at each moment.
Conclusion
The problem is not that the Euribor rises or falls.
The problem is making decisions based on information that is no longer valid.
And with a mortgage, that translates into money.
How to analyse your case
Today more than ever, it is important to know all available options before making a decision.
At Hipotea we analyse each case personally, comparing different market alternatives and seeking the most suitable option for each situation.
The assessment is free.