Skip to content

A worrying trend in the mortgage market
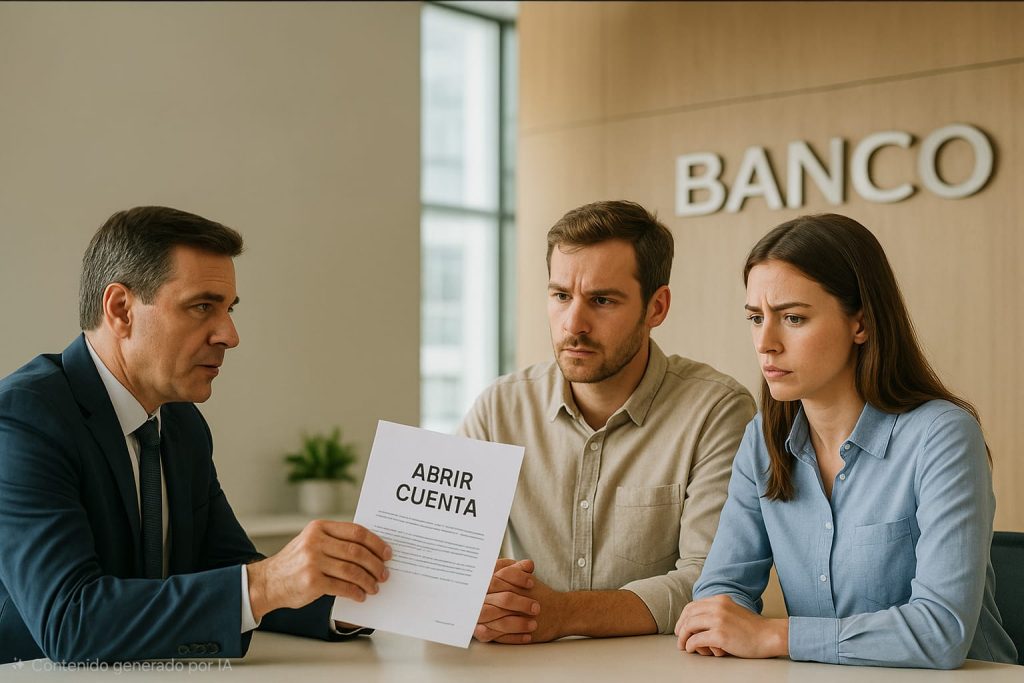
In recent months a worrying practice has begun to spread among some banking entities and certain mortgage brokers: requesting personal data or demanding to open a bank account even before offering a mortgage.
Although it may seem like an innocent procedure, behind this gesture lies a customer retention strategy that can make you lose freedom to negotiate and, in many cases, money.
What does this “bad practice” consist of?
Some banks are requesting customers to open an account to “study their case”. However, the Law 5/2019 on Real Estate Credit Contracts makes clear that no entity can force you to contract an additional product that is not necessary for granting the loan.
Once the customer opens that account, the bank already has their data and an internal file opened, making it difficult for another intermediary or even another branch of the same bank to present a better offer. In practice, the customer becomes “tied” to that entity, limiting their ability to compare.
The other side: brokers who block your file
The problem is not limited to banks. Some mortgage brokers—especially those advertising “our services are free, we are paid by the bank”—are requesting the ID card and all personal data from the customer before showing a single offer.
With that information, they send the file to several entities to register the operation under their name. Result: the customer is blocked and other intermediaries can no longer process the mortgage on their behalf.
This occurs because in the Spanish banking system, once a file is associated with a particular broker, the rest are automatically discarded, even if the customer has signed nothing.
Why this happens: commissions and preferential relationships
These types of intermediaries work only with a limited number of banks with whom they have commission agreements. Therefore, they do not truly negotiate each operation: they simply send the customer's data and it is the bank who responds with its standard offer.
There is no personalised analysis, no optimisation of conditions, nor a global comparison. And most worrying, the customer believes they are already “in process” and loses the opportunity to improve their mortgage with a truly independent professional.
How to avoid falling into this trap
- Do not open a bank account just to have them study your case. They are not authorised to require it.
- Do not provide your passport nor your personal data until they present you with a real simulation with initial conditions.
- Be wary of brokers who say “we don't charge you”. If they don't charge you, someone else pays them, and that affects their independence.
- Demand transparency: ask them to detail in writing if they work with all banks or only some.
- Always check that the intermediary is registered with the Bank of Spain as a Real Estate Credit Intermediary (ICI).
The role of the independent mortgage advisor
An independent advisor works for the client, not the bank. Their role is to negotiate real conditions, tailored to the profile and needs of each buyer.
And although they may charge fees for their service, these usually more than compensate for themselves thanks to the savings obtained by negotiating rates, commissions or unnecessary agreements.
Furthermore, many advisors — like at Hipotea — offer a free and no-obligation preliminary study so that the client can decide whether it is worth continuing, without risk or obligation.
Conclusion: your data is power, protect it
The personal and financial information you provide has value.
Handing it over without control can limit your freedom to negotiate and influence one of the most important financial decisions of your life: your mortgage.
Therefore, before signing, opening accounts or sending documents, inform yourself well and compare.
And if you believe you have already been a victim of one of these practices, you can file a complaint with the Bank of Spain or the consumer authority of your autonomous community.