 Skip to content

For weeks, the Spanish mortgage market conveyed a certain sense of stability. But that picture has started to change. The environment has become more uncertain, the euribor has risen, and regulators have begun to signal caution.
We are not facing a widespread mortgage crisis. The problem is different: the margin for mistakes is shrinking. And that completely changes how to decide whether to get a mortgage now, wait, or review one you already have.
Euribor exerts pressure again
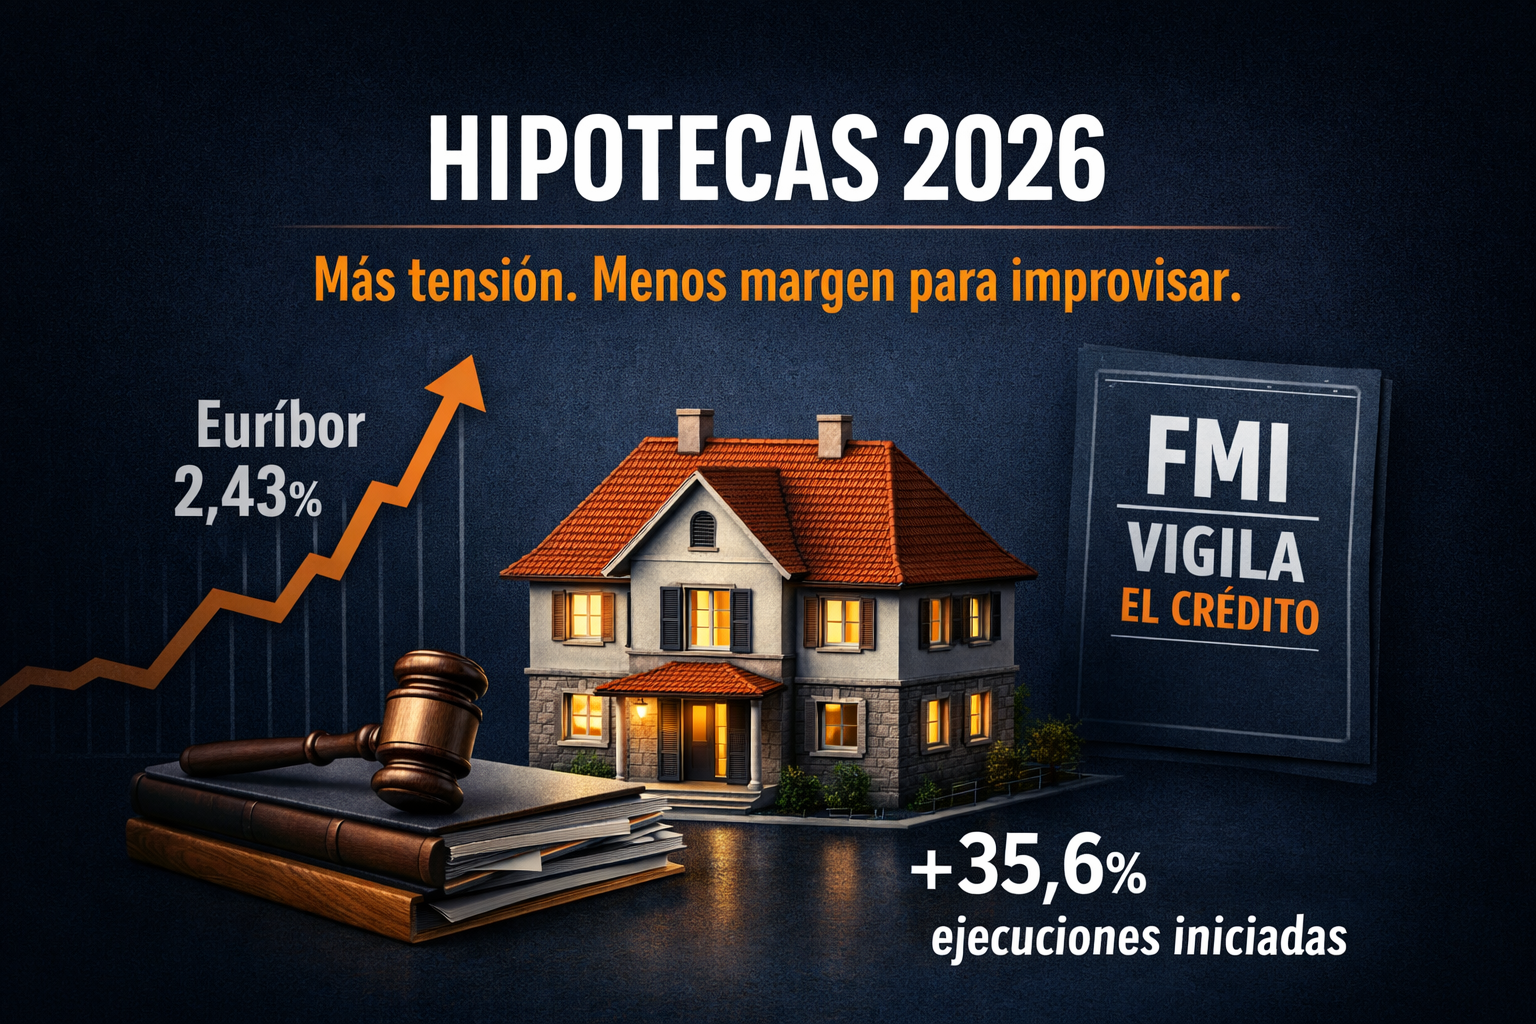
The first clear sign is in the euribor. The official rate for February was 2,221%, but in March the daily reference sharply rose again. On 22 March it reached 2,65%, a provisional average of 2,43%. This represents an increase of almost 10% compared to March in just 23 days.
This matters far more than it seems. When the euribor rises, it not only affects those who already have a variable-rate mortgage. It also influences how banks set prices, adjust margins, and assess the risk of new loans. In other words: financing is starting to become less favourable.
Waiting in this context ceases to be a neutral decision. Because although changes may not always be noticeable overnight, they can translate into worse terms, less banking flexibility, and reduced negotiating power for the buyer.
Mortgage foreclosures are increasing, but the data needs to be interpreted carefully
The second warning sign is the rise in initiated mortgage foreclosures. In 2025 they increased by a 35,6% and reached a total of 31,416 proceedings in Spain.
This is a serious figure and should not be downplayed. However, it should not be interpreted simplistically either. It does not in itself mean we are entering a new mortgage crisis like the one years ago. It is a lagging indicator reflecting accumulated pressures, not an exact snapshot of the present.
In fact, the judicial report itself shows another relevant nuance: evictions carried out in 2025 were 24.540, a 11% fewer than the previous year. Of those, 18.317 were linked to rentals and 4.346 to mortgage foreclosures. In other words, the data is alarming, yes, but does not justify talk of a mortgage collapse.
Furthermore, there is a very clear territorial concentration. Catalonia led the foreclosures with 9.370, followed by Andalusia with 6.466, the Valencian Community with 3.530 and Madrid with 2.889.
The correct interpretation is not alarmism. The correct interpretation is caution.
The IMF focuses on credit easing
The third element of the analysis is probably the most important. The IMF has warned that, in a context of rapid house price rises and initial signs of loosening lending standards, Spain should begin to introduce macroprudential measures related to mortgages, at least as supervisory guidance.
This warning does not mean the system is out of control nor that banks are lending irresponsibly. What it highlights is something more subtle: if housing prices continue to rise strongly and more transactions with demanding financing levels begin to appear, risk may start to accumulate quietly.
This nuance is key. Because problems often do not emerge when everything seems bad, but when the market appears normal while the safety margin is being narrowed.
A more open but also more fragile market
Here an important idea emerges. In recent months, the previous monetary easing had facilitated credit access for profiles who previously found it more difficult. But at the same time, the new uncertainty context is again putting pressure on the market.
That is why some voices in the sector already recommend not delaying mature transactions. The reasoning is clear: if inflationary pressures persist and banks tighten prices or conditions, acting later may be more costly.
However, here is the true professional nuance: advancing a mature signing is not the same as rushing a poorly structured transaction.
Some buyers can benefit from acting now. Others do not need to rush, but to better prepare their application, organise documents, strengthen savings, or calmly analyse which lender truly fits their profile.
So, what is advisable to do now?
The key is not to be in a hurry. The key is not to be too late.
Because advancing a mature signing can be a sound decision. But rushing a poorly prepared deal can go wrong. Just as waiting out of habit, trusting that in a few months everything will be easier, can also end up costing money.
The fundamental conclusion is clear: the mortgage market is not saying everything will go badly. It is saying something more useful and uncomfortable: the margin for improvisation is running out.
In this context, the problem is no longer just obtaining a mortgage. The real challenge is obtaining the right one, at the right time, and with the correct strategy.
That is why, if you are thinking about buying a home, switching your mortgage, or simply want to know if this is your moment, it is unwise to decide on intuition. It is wise to carefully analyse your profile, truly compare offers, and act with judgement before the market changes further.


