 Skip to content

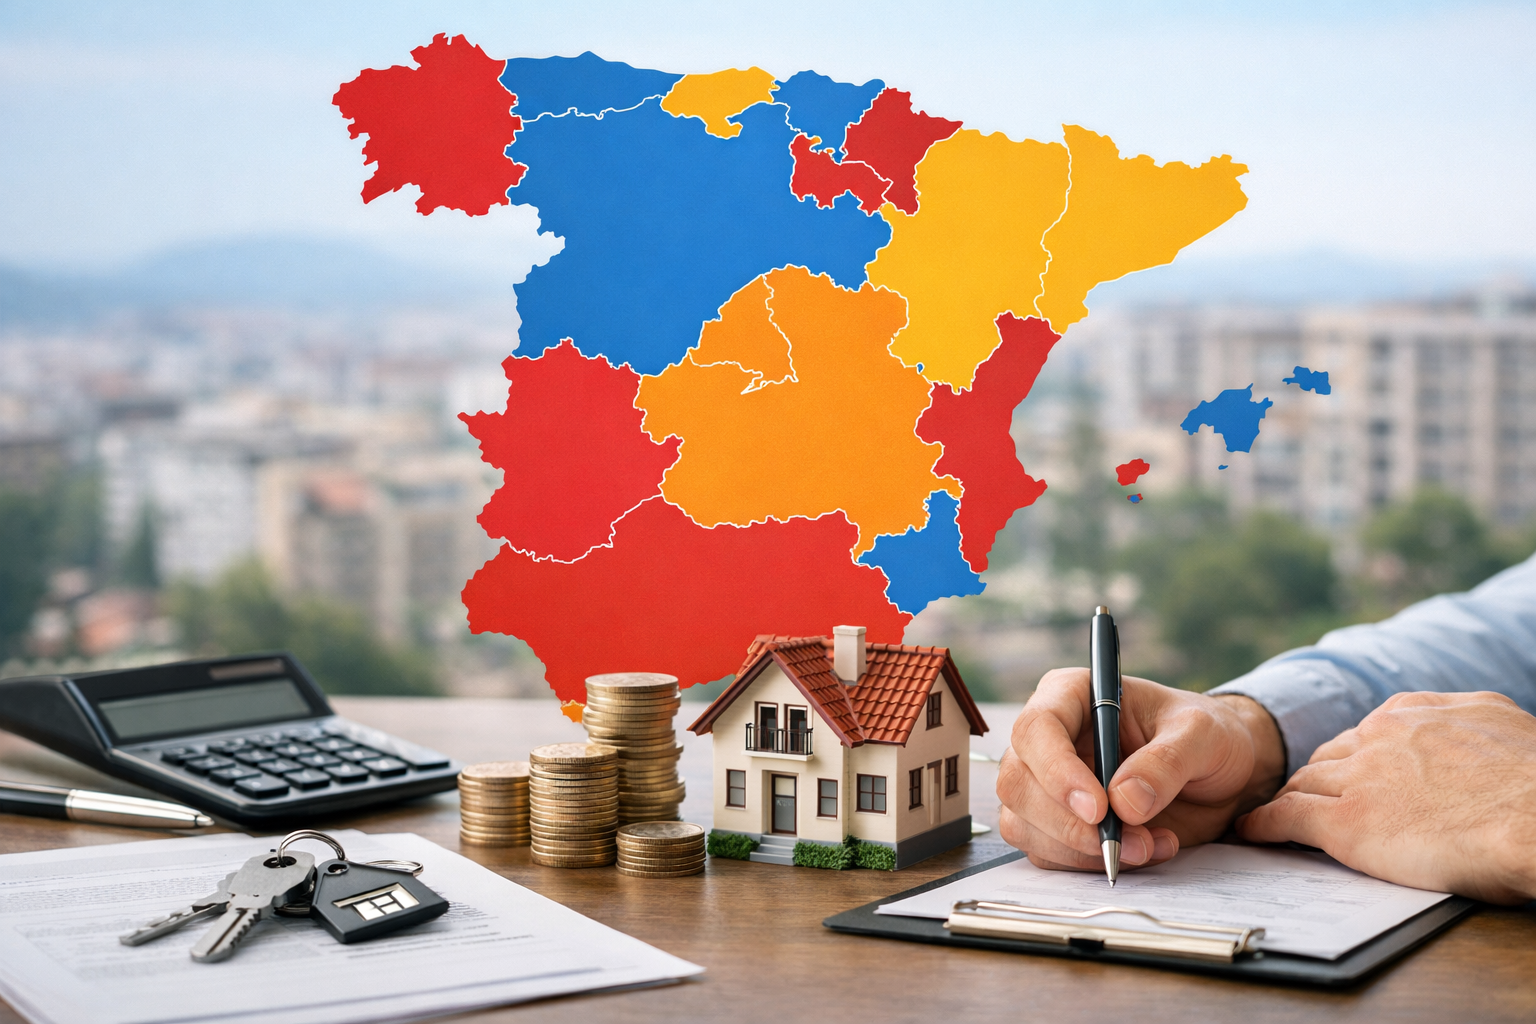
Buying a home with less than 20 % savings remains one of the biggest challenges for many people in Spain. In recent years, the government has launched various public guarantee mechanisms to facilitate access to financing, but not all work the same nor are available throughout the territory.
Following the extension of the state ICO guarantee, many autonomous communities have developed — or reinforced — their own mortgage guarantee programmes, with different conditions, requirements, and procedures.
This article focuses exclusively on regional guarantees in 2026, explaining:
- what they are,
- how they differ from the Government guarantee,
- and which communities currently have active programmes.
What is a regional mortgage guarantee?
A regional mortgage guarantee is a public guarantee offered by an autonomous community to assist certain buyers in obtaining a mortgage with a higher level of financing than usual.
In practice, these guarantees allow:
- exceeding 80 % financing,
- reducing the need for prior savings,
- facilitating access to the primary residence, especially for young people and families.
Unlike the state ICO guarantee, each autonomous community sets its own rules:
- maximum age,
- income limits,
- maximum property price,
- guaranteed percentage,
- and the banks they operate with.
Key differences between ICO guarantee and regional guarantee
Although both pursue a similar objective, they are not the same thing:
- The ICO Guarantee the ICO is a state programme, homogeneous and with common criteria throughout the country.
- The regional guarantees are territorial programmes, with specific rules per community.
Additionally:
- Not all banks work with all regional guarantees.
- Operations, deadlines and documentation can vary significantly.
- In some cases, the regional guarantee may be more flexible than the ICO; in others, more restrictive.
That is why it is important to understand what exists in each community.
Communities with ACTIVE regional guarantees in 2026
As of 21 January 2026, these are the communities with operational regional mortgage guarantee programmes:
Andalusia
Guarantee programme for first-time buyers, aimed at facilitating high financing. In practice, it is applied with extended terms and criteria adapted to young and family profiles.
Community of Madrid
“My First Home”, one of the best-known programmes, allowing higher financing through regional public guarantee.
Balearic Islands
“Hipoteca Jove”, with extended validity and updated limits, focused on residents and primary home buyers.
Basque Country (Euskadi)
GazteAvala / Gazte-aval, a specific guarantee line for young buyers.
Valencian Community
IVF guarantees IVF for first homes, with active call and operation in 2026.
Region of Murcia
ICREF Young Guarantee, extended until 31/12/2026 or until funds run out.
Extremadura
Young Housing Guarantee, regional guarantee line to facilitate access to purchase.
Galicia
Regional guarantee programme for property acquisition, with active calls in 2026.
Castile and León
“My First Home”, extended to the 2026 fiscal year.
La Rioja
AvaLa Rioja, active programme through IRVI.
Communities with announced but NOT yet operational guarantees
In these communities there are announcements or public declarations, but no clear and open operations comparable to those above:
- Cantabria
- Canary Islands
If official orders or calls are published, they could be added to active programmes.
Communities WITHOUT active or announced regional guarantees
As of today, no official evidence has been found of regional mortgage guarantee programmes in:
- Aragon
- Asturias
- Castilla-La Mancha
- Catalonia
- Navarra
- Ceuta and Melilla
In these communities, access to high financing depends mainly on the state guarantee or the internal policy of each banking institution.
Can a regional guarantee be combined with the ICO guarantee?
This is one of the most frequently asked and also one of the most complex questions.
In practice:
- it is not always possible to combine both guarantees,
- it depends on the bank,
- the client’s profile,
- and the specific design of each regional programme.
Some communities view their guarantee as an alternative to the ICO; others as a potential complement. There is no single rule.
Common mistakes when trying to use regional guarantees
One common problem is thinking that the guarantee:
- automatically guarantees the mortgage,
- or that any bank will apply it.
In practice, the most frequent mistakes are:
- applying at non-participating institutions,
- not meeting income or price limits,
- not fitting the financial profile,
- or overlooking the property valuation.
Why mortgage advice is key in these cases
Regional guarantees are not standard products. Each transaction requires:
- prior analysis,
- matching with a specific bank,
- guidance in processing: required documents and procedures,
- and coordination between public regulations and banking criteria.
Without specialised advice, it is easy to miss a real opportunity due to a technical detail.
Conclusion: guarantees exist, but do not work the same for everyone
In 2026 there are real public guarantees to facilitate home purchase, but:
- they depend on the region,
- the buyer's profile,
- and how the operation is structured.
Knowing what each community offers is the first step. Knowing how to use it correctly, is the decisive one.


